
- Cashless ATM isn't a real payment method — it routes purchases as ATM cash withdrawals (MCC 6011), tacking on a $3.50+ surcharge and a confusing bank statement line.
- Visa and Mastercard have flagged this routing as a terms-of-service violation, and state regulators are treating it as a potential licensing risk — exposure that can cost you your merchant account overnight.
- The fee and the confusion erode customer trust; ACH customers spend 15–35% more per transaction than cash or cashless-ATM customers.
- ACH also removes the manual reconciliation burden CATM creates, and switching is faster and smoother than most operators expect.
Every dispensary owner who has used a cashless ATM knows the tension. Cannabis is federally illegal, which means most banks won't touch you, card networks won't play nice, and your customers are stuck digging through their wallets for cash — or you're watching them walk out empty-handed.
So when cashless ATM solutions showed up promising a fix, operators jumped. It worked, sort of. Customers could tap a card. Sales went up. Problem solved.
Except it wasn't.
The cashless ATM — sometimes called CATM, sometimes dressed up as a "point-of-banking" terminal — was never a real payment solution. It was a workaround wrapped in a user experience that deliberately obscured what was actually happening. And now, years later, the bill is coming due.
What a cashless ATM actually is (and what it tells your customers)
Here's the mechanics: when a customer pays at a cashless ATM terminal, the transaction isn't processed as a debit card purchase. It's routed as an ATM cash withdrawal. The terminal shows a surcharge — often $3.50 or more — and the customer technically "receives cash" that gets applied to their purchase.
None of that is what the customer thinks is happening. They see a card reader. They think they're paying. What they're actually doing is withdrawing cash through a machine that doesn't dispense any cash.
That's the first problem: it's confusing at best, and deceptive at worst. When customers see their bank statement, they don't see "Dispensary Purchase." They see an ATM transaction, often at a location that doesn't match where they shopped. That's a recipe for chargebacks, complaints, and lost trust.
The second problem is the fee. A $3.50 surcharge on a $40 purchase is nearly a 10% tax on choosing to shop with you — and that's before the round-up and out-of-network fees. Some customers swallow it. Many don't. And every single one of them remembers it.
The regulatory walls are closing in
Cashless ATMs have operated in a gray zone since their introduction. But that gray zone is shrinking — fast.
Visa and Mastercard have put dispensaries on notice. The card networks know these transactions are being misclassified — routed under MCC code 6011, the merchant category code reserved exclusively for ATM cash withdrawals, so a $40 flower purchase looks to the network like someone pulling cash from a machine. Both networks have called this out directly: Visa moved to kill cashless ATM in cannabis, and Mastercard told processors to stop marijuana purchases on its debit cards. They've identified cashless ATM routing as a terms-of-service violation and have been increasingly aggressive in pulling merchant accounts and flagging processors who facilitate them. When a processor gets flagged, every dispensary they serve can lose access overnight — no warning, no grace period.
No warning, no grace period. When a processor gets flagged by a card network, every dispensary it serves can lose payment access overnight.
State regulators are paying attention. A growing number of state cannabis regulatory bodies have begun scrutinizing payment processing at licensed dispensaries. Regulators in several markets have signaled that facilitating transactions through deceptive payment flows — or through channels that misrepresent the nature of purchases — could constitute a licensing violation. For a business where the license is the business, that risk is existential.
Banks are asking questions. If your dispensary's payment activity is flagged by your banking institution for suspicious classification patterns, you risk losing your merchant account, your business banking relationship, or both. These aren't hypothetical threats. They're happening to dispensaries right now.
The customer trust problem you can't quantify (but absolutely feel)
Regulatory risk is measurable. Customer erosion is harder to see — until it's too late.
Think about what the cashless ATM experience actually communicates: we want your money, but we can't make this easy for you. There's a surcharge. There's a confusing receipt. There's a moment where the customer wonders if something sketchy is happening.
Cannabis retail is a trust industry. You're building brand loyalty in a category where customers have options — dispensaries on every corner in mature markets, delivery services a click away. The payment experience is part of the brand experience. A clunky, fee-heavy, confusing checkout isn't neutral — it's a signal.
Meanwhile, ACH payment customers behave differently. Internal data from BLAZEPAY ACH-enabled dispensaries shows that customers who pay via ACH spend roughly 30–35% more per transaction than cash customers, and about 15–20% more than cashless ATM customers. These aren't accidental shoppers. They're engaged, returning customers who have chosen to connect their bank account — a real commitment signal.
The checkout experience shapes that relationship. ACH delivers a clean, modern flow with no surcharge and a receipt that actually reflects what happened. That's a transaction your customer can explain to their partner. That's a statement line that doesn't look alarming.
The reconciliation tax nobody talks about
There's an operational cost to a cashless ATM that never shows up on the sales pitch slide.
Because CATM transactions are routed as ATM withdrawals, the transaction records don't flow cleanly into most point-of-sale systems. Reconciliation becomes a manual process — matching ATM receipts against sales records, chasing down discrepancies, explaining unexplained fees to the accountant. For a multi-location operator, this compounds weekly.
Dispensary back-office teams are already stretched. The reconciliation burden created by CATM is invisible until someone has to do it — and then it's a half-day every week, minimum.
ACH eliminates this. Transactions are categorized correctly from the jump. Reporting is clean. Closeout is fast.
What to expect when switching from cashless ATM to ACH
The operators who've moved off cashless ATM consistently report three things.
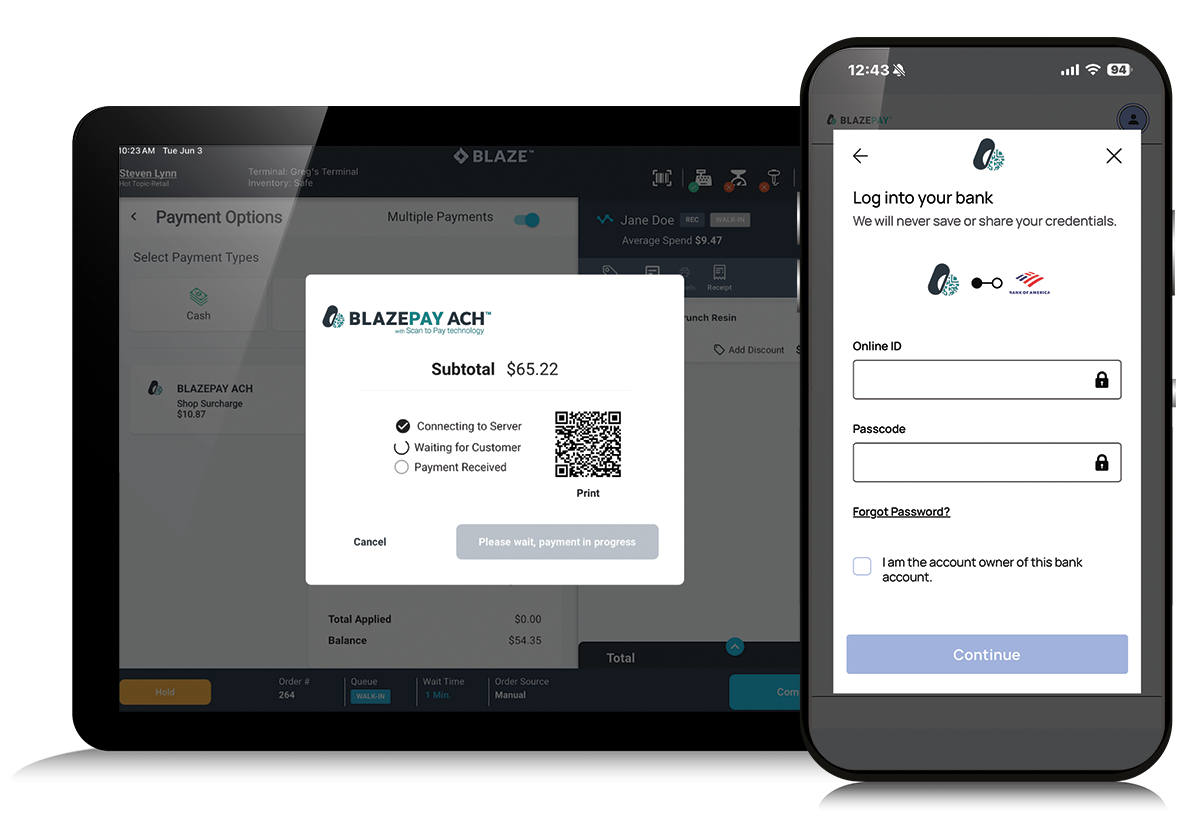
First, the transition is smoother than expected. Customers adapt quickly when given a clear alternative. BLAZEPAY ACH uses a customer-facing enrollment flow that's mobile-friendly and fast — most customers complete it in under two minutes at the register.
Second, the fee complaints stop. When your checkout doesn't carry a $3.50 tack-on, the friction point disappears. Customers stop asking about it. Budtenders stop apologizing for it.
Third, the data gets useful. With clean ACH transaction records feeding into your POS, you can actually track payment-type behavior over time — who's returning, what they're spending, where the retention opportunity is.
Ready to Leave Cashless ATM Behind?
See how BLAZEPAY ACH gets your dispensary to compliant, low-friction payments — without the surcharge, the confusing receipts, or the regulatory exposure.
Where do you stand?
The question isn't whether a cashless ATM is a long-term solution. It isn't. The question is how exposed you are right now, and how quickly you need to act.
Some operators are running significant regulatory and reputational risk without realizing it. Others have already started the transition and are seeing the results. Most are somewhere in the middle — aware of the problem but uncertain about the path forward.
That's exactly what the Cashless ATM Risk Scorecard below is designed to help you figure out.
It takes about three minutes. You'll come out with a clear picture of your current exposure across four dimensions: regulatory risk, customer friction, reconciliation burden, and banking relationship health.
Cashless ATM FAQs
Is a cashless ATM legal for dispensaries?
Cashless ATMs operate in a shrinking legal gray zone. Visa and Mastercard have identified cashless ATM routing as a terms-of-service violation, and a growing number of state cannabis regulators are scrutinizing the practice as a potential licensing issue. It's increasingly treated as non-compliant rather than merely risky.
How does a cashless ATM transaction actually work?
Instead of processing as a debit purchase, the payment is routed as an ATM cash withdrawal. The customer is charged a surcharge — often $3.50 or more — and "receives cash" that's applied to their purchase, even though no cash is dispensed. On a bank statement it appears as an ATM transaction, not a dispensary purchase.
What are the fees on a cashless ATM?
A typical $3.50 surcharge on a $40 purchase is nearly a 10% fee — before round-ups and out-of-network charges. Those fees are visible to customers and are a common source of friction and complaints.
Is ACH a better payment option for dispensaries?
Yes. ACH delivers a clean checkout with no surcharge, a receipt that accurately reflects the purchase, and transaction records that flow correctly into your POS — eliminating manual reconciliation. BLAZEPAY data shows ACH customers spend roughly 15–20% more per transaction than cashless ATM customers.